Specified personal savings
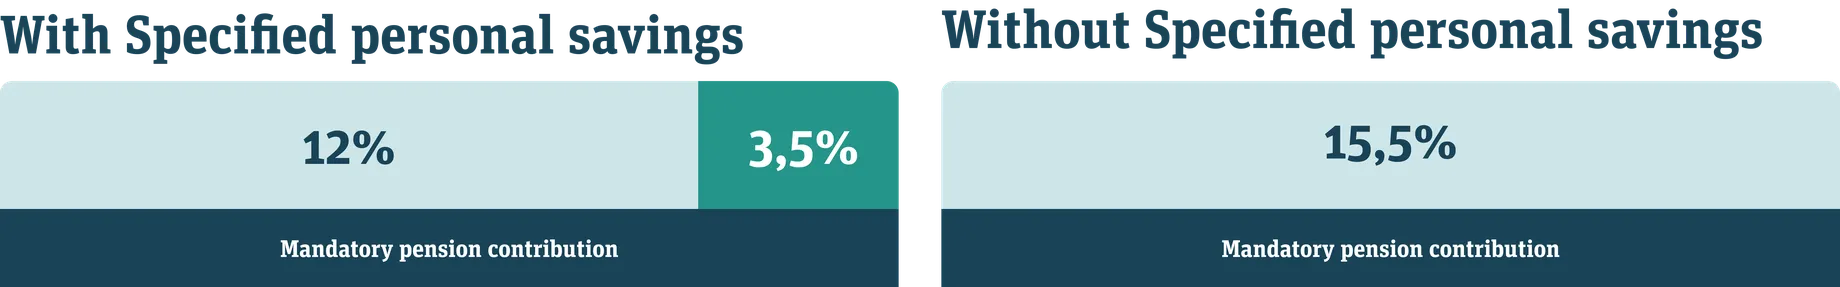
You can allocate up to 3.5% of your pension contribution to Specified personal savings, which is governed by rules similar to those for a Private Pension.
Specified personal savings form part of your mandatory pension contributions and are held in your name. They are inheritable, offer a choice of investment options, and can provide greater financial flexibility later in life.
Apply for Specified personal savingsWhat is Specified personal savings?
The mandatory pension contribution in Iceland is generally 15.5% of your salary. Up to 3.5% of the contribution may be allocated to Specified personal savings.
Your savings are held in your name, are inheritable, and can be invested in a range of investment options. Subject to certain conditions, they may also be used tax-free towards the purchase of your first home.
Investment options for everyone
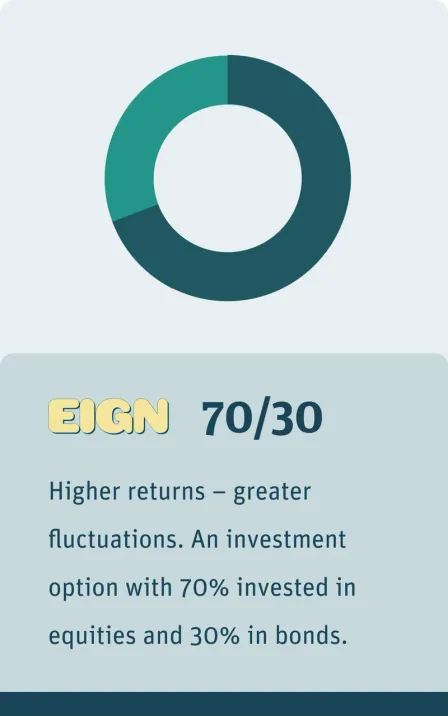
Specified personal savings can be invested in the same way as a Private Pension. Gildi offers five different investment options, making it easy to choose the one that best suits your needs.
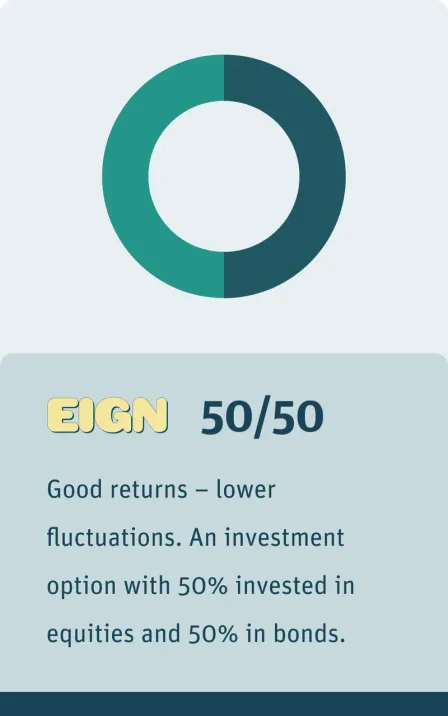
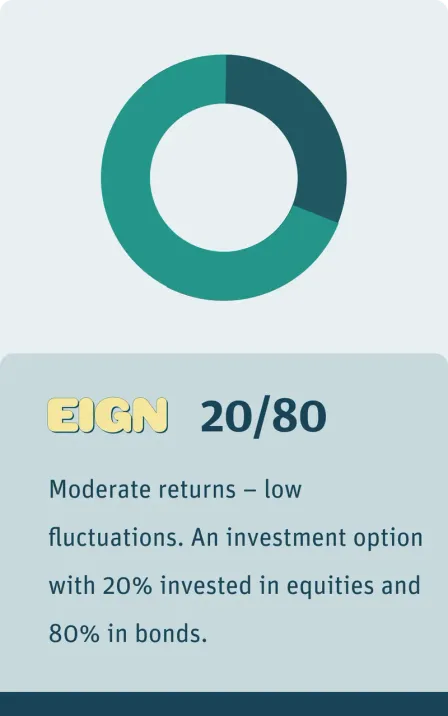
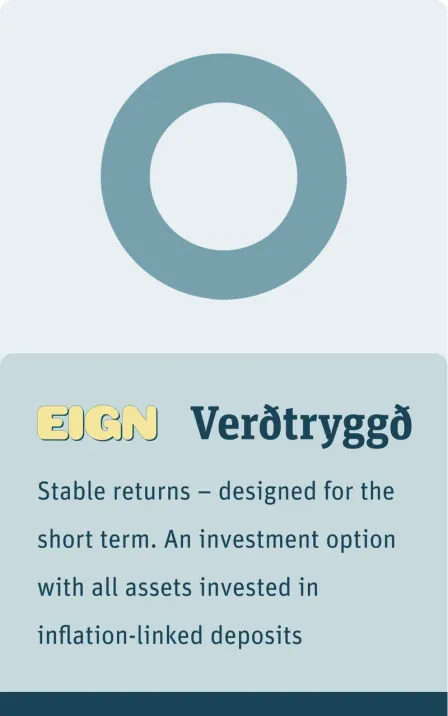
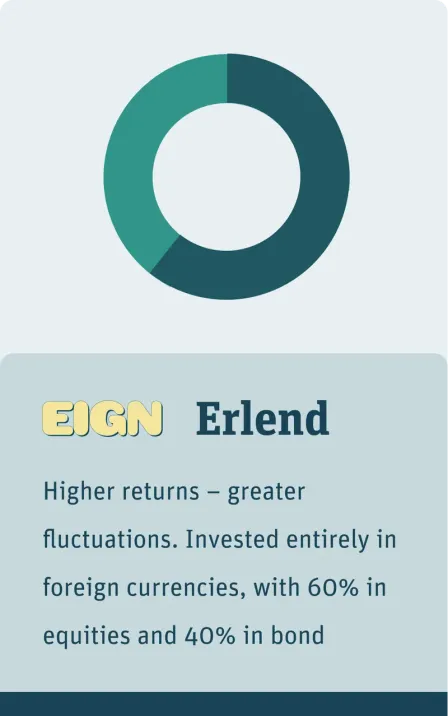
Benefits of Specified personal savings:
- Savings held in your name
- Inheritable savings
- Choice of investment options
- Greater flexibility in retirement
- Switch investment options at any time at no cost as your needs or goals change
- May be used tax-free towards the purchase of your first home, subject to certain conditions
Is Specified personal savings right for me?
Specified personal savings may be a good choice if you want greater control over your retirement savings and the opportunity to build inheritable assets. They are generally best suited to people who are around halfway through their working life. If you also contribute to a Private Pension, your combined private pension contributions can total up to 9.5% of your salary before tax.
At the same time, it is important to remember that allocating part of your pension contribution to Specified personal savings means that less is paid into the collective pension scheme. This may affect your entitlement to lifelong retirement benefits, as well as disability and surviving spouse pensions. That is why it is important to consider the overall impact before making a decision.
We recommend looking at the full picture—including the impact on your collective pension benefits, future payments and long-term goals—before deciding. We also encourage you to use Gildi's pension calculator to see how the different options may affect your retirement.
FAQ:
Specified personal savings may be a good choice for those who want greater control over how their savings are invested, wish to build inheritable assets, and would like greater flexibility later in their working life.
A Private Pension may be a good choice for those who want to increase their retirement savings, benefit from their employer's matching contribution, and build a flexible supplement to their other pension benefits.
Yes. Your Specified personal savings are inheritable in accordance with the applicable rules.
Special provisions may apply in certain circumstances, such as disability or death.
Yes. Choosing Specified personal savings affects the pension rights you build up in the collective pension scheme.
Because a smaller share of your pension contribution is paid into the collective scheme, you build up fewer pension rights there. As a result, your lifelong retirement pension, disability pension and surviving spouse pension will be lower than they would otherwise have been.
Gildi offers a wide range of investment options designed to suit different needs, and we naturally encourage you to choose Gildi.
However, the answer is no. Specified personal savings can also be invested with other providers. Investment options are available through pension funds, banks and other investment managers. Costs vary considerably, so we encourage you to compare fees and other terms carefully before making a decision.
You can only use Specified personal savings if you qualify for the First Property Scheme.
If you already own a home and are using the General Property Scheme, this is not available.
However, you can always use your Private Pension to make tax-free payments towards your mortgage, subject to the applicable rules.